Why I’m Passing on Options for Prediction Markets (For Now)

The appeal is real. The opportunity isn’t.

A project called Convallax shipped a testnet recently billing itself as the first options exchange on prediction markets. It lets you trade vanilla options (calls and puts) not against an event’s outcome, but against the implied probability of that outcome—the price of the YES contract—at a range of strikes and terms leading up to settlement. I read the announcement with more than passing interest because it’s something I explored earlier this year and decided not to move on.

This isn’t a takedown—I’d love to see it succeed. But it collides with the same core problem plaguing the entire event contract space: the need for sustained, informed participation beyond short-term sports betting. Or, less cynically, it needs informed investors looking to trade economic markets over the long term. I’ve had a hard time finding these people and am starting to wonder if they’re ever going to emerge.

The appeal of what a robust options market over event contracts could offer is real. Unfortunately, the opportunity itself isn’t.

Selling Real Estate in a Ghost Town

The hardest problem any options exchange faces in this space is that there’s no durable volume to build on. The activity that exists is overwhelmingly short-horizon (sports outcomes resolved in hours or days). That’s real volume, but it’s the wrong kind. An options layer needs an underlying that people hold and care about across weeks and months, not a market that’s created and settled before an option on it could ever season. If you can’t get traders excited about the underlying market in the first place, you won’t get them excited about trading dozens of option series struck against it.

Consider an arbitrary market trading at 50% that settles at year-end. If you offer monthly options around that level for the rest of the year you’ll end up with 90 unique series: 2 (put and call) × 9 (strikes from 30% to 70% in 5% steps) × 5 (expiries July through November). How much volume on the underlying would you need to justify demand across all 90? I don’t think even the 2028 US presidential election outcome has a realistic shot of delivering the meaningful and sustained volume required.

No Yield, No Patient Capital

There’s a structural reason the long-horizon participants an options layer needs are so scarce, and I wrote about it after the Seahawks, of all things, exposed it. When you hold a prediction market position that settles months out, your money is parked. The honest way to value it is against what it would earn risk-free in a Treasury over the same period (let’s say 4.4% today). That opportunity cost is the real breakeven. If the platform pays you no yield on the position, holding it is expensive, and patient capital simply won’t show up.

That’s exactly Polymarket’s situation: it pays interest on only a small, handpicked set of long-term political markets, and nothing on the rest. As a result, most of their long-term markets have very little volume. It’s just people with views so strong they’re willing to eat the price of the contract plus the opportunity cost of carrying.

In addition to the low volume numbers, the lack of institutional liquidity means that these markets can be susceptible to manipulation through very thin order books. This was also covered in the Seahawks article referenced earlier.

How Are You Pricing?

Set demand aside and suppose the participants showed up. Pricing these options isn’t as straightforward as vanillas on underlyings like stocks or indexes.

Equity options control 100 shares each. Here each option is 1:1 with the underlying contract, so the notional is tiny and you need enormous order counts to add up to anything. Worse, with no continuous price process underneath, there’s little to separate adjacent expiries. The tick size starts to become an issue when trying to keep the whole thing liquid and coherent.

Consider a market currently at 50% settling in six months. How do you value the 70% call four months out versus five months out if there’s no expected catalyst in that window? It’s hard to justify pricing them apart by much, and if you try, you’re fighting to keep the term structure monotonic since a longer-dated option must be worth more than a shorter one at the same strike. Thin, model-free quotes drift into exactly that kind of arbitrageable mess.

Underlying Exchanges Have The Ultimate Option

But suppose you solved pricing and proved the demand. It actually gets even worse because an options exchange in this space has no moat against the event contract exchange itself. Anything an entity like Convallax can offer, the underlying venue like Polymarket can mint natively. A ladder of plain over/under contracts—“Will this market finish [month] at or above [strike]?” at each month and strike—spans every call, put, and spread you could write.

Take the cleanest case, a 65/70 call spread. Its entire value is captured by just two native over/unders. It’s worth roughly five cents times the average of the 65 and 70 over/under prices. The two rungs bracket the spread—the 65 pays out a touch too early, the 70 a touch too late—and their average tracks it.
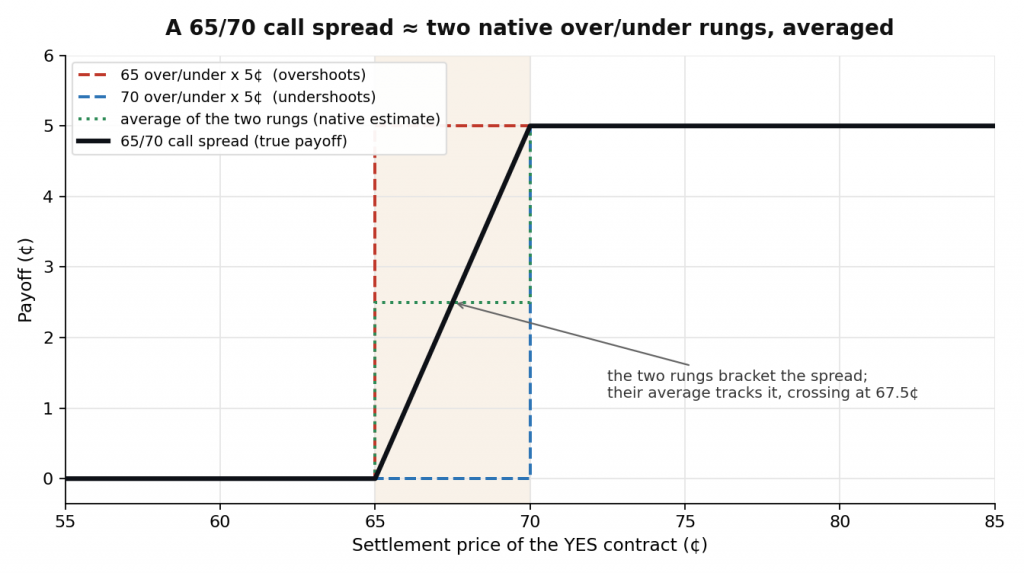
An outright call is slightly more involved because it requires a strip of those over/unders stacked from the strike upward. Either way, every option is a static basket of contracts the exchange can already issue, available with position netting from the account a trader already uses, and spinning up a fresh over/under at any strike or expiry costs the venue essentially nothing. So even in the world where demand exists and pricing is solved, the exposure people want is one the exchange itself supplies more cheaply. And the third-party options layer is left with little value to offer.

To be fair, there are edge cases where vanillas cover specific things the binaries can’t. But is it enough to justify the investment? Is there really a convexity play to be constructed over an underlying outcome settling in six months and averaging a few thousand dollars in volume per day?

Is the Word “Implied” Implied?

One claim I’ll push back on directly is the promise of volatility surfaces for the underlying markets. Most readers will interpret this as implied volatility surfaces extracted from live, two-sided order books in deep markets like equity or index options. A surface that a single firm simply publishes on its own isn’t particularly useful or credible. It needs to reflect real market consensus across strikes and expiries.

And that’s the problem. Convallax doesn’t operate like the continuous quoting environments that produce reliable implied surfaces. Instead, it uses a request-for-quote (RFQ) model: an option is priced only when someone specifically asks for it. There are no resting, continuous bids and offers across the full grid of strikes and expiries. Without that depth and liquidity, there’s simply no organic market data from which a meaningful implied volatility surface can be derived.

I understand the practical reasons for sticking with RFQ—you’d need exactly the broad, standing demand we’ve already established isn’t there yet. But marketing the idea of an implied surface that the current structure can’t realistically produce feels aspirational at best. It’s the kind of overreach that makes me want to re-examine everything else with extra scrutiny.

What It Leaves

I believe the idea of options on event contracts is a nonstarter for the foreseeable future. That’s not because anyone involved is wrong about something technical, but because the foundation isn’t there. No durable demand, no patient capital to create it, no tractable way to price the surface, and no moat even if all three were solved.

This doesn’t mean options on events are a dead idea forever. They just belong where the liquidity already lives—written on underlyings deep and continuous enough to support them (like Cboe with S&P 500 contracts)—not bolted onto thin standalone markets that can’t yet carry their own weight. The appeal was always real. The opportunity may be too, just somewhere else.
Who Is Cboe’s S&P 500 Prediction Market Actually For?

Opportunistic marketing or a path to an event contracts future?

I have, it turns out, been living in The Plus Zone for years without knowing it. That’s Cboe’s name for the sloped middle of a vertical spread—the part that pays out proportionally between the strikes—which I’d always thought of as simply how a spread works. Apparently it’s a feature now, and an admirably well-named one. My hat is off to the marketing wizard to coined that one—I’ve been in your exact situation and recognize your game.

But the branding really does work. I laughed out loud when I read the description, and that made me curious enough to read the actual filings. The deeper I went, the more I kept circling one question. It’s not whether this thing is gambling (the fight the media savors) but rather who it’s actually built for.

Cboe’s own documentation says as much: the verticals are “not a separate product” but rather “standard XSP vertical spread strategies.” So if you buy one, you’ll end up with a call spread in your book. As a result, it also requires options spread approval on your account.

Are prediction markets crossing over already?

Last week, Schwab announced that they would soon be supporting these spread products through a partnership with Cboe. But what really stood out to me was that both they and Cboe position them as “prediction markets.”

I’ve regularly used Schwab as a landmark in my exploration of what it will take to get broad adoption of event contracts in mainstream finance. I’ve made cases about the risk of the toxic term “prediction markets” and the need for consolidated clearing across multiple competing exchanges, plus several other missing pieces I thought were blockers to the new asset class.

But it turns out that I was overthinking it. The missing piece was the humble call spread.

The experienced options traders out there may ask, “if it’s just a 0DTE call spread on XSP with a $1 strike width, can I just trade them on my own today?” The answer is yes. Yes you can.

They’re not exactly what I’d consider “prediction markets,” but I’m also the guy who had no idea about The Plus Zone until the press release came out, so maybe my expertise has reached its limit.

But what if The Plus Zone is too much for me to handle?

Good news—they’ve thought of that, too. Alongside the XSP vertical spread product they’re also going to support a true binary threshold contract. It’s effectively the same as the spread, except that there’s no Plus Zone. I’ve suggested “The Plus Zone Minus” as the official name of this new offering, but I’m pessimistic.

This product is simply a Yes/No contract for questions like “Will XSP close at or above $750?” It’s a little trickier to hedge given the jump payoff, but that’ll get baked into the pricing. Plus, it’s a lot closer to the prediction markets you see on exchanges like Kalshi.

So then who are these markets for?

Let’s work down the list.

  • Not the prediction market audience. People who want a simple yes/no without an options account can’t access them. A fraction of the Kalshi and Polymarket crowd might cross over, but I’m skeptical—the options-approval gate is exactly the friction they came to those platforms to avoid.
  • Not active options traders. Anyone with options approval can trade these same spreads directly, at any width or expiry, and adjust or roll them. The packaged version only removes that flexibility. I’m skeptical they’d ever want the pure binary version.
  • Not hedgers. 0DTE and 1DTE options have very limited utility when it comes to hedging. Outside of the few big macro events like Fed decisions or CPI prints, they’re just not useful.
  • Not position traders. No term structure and dollar-wide zones mean there’s little to build.
  • Not institutions. They already have the full options toolkit.

This really only leaves two groups. The first are users who are able to “prove” their option competence enough to get spread approval but not capable enough to trade them properly.

The second are amateur automated traders. These are the people convinced on Reddit and Discord that they could vibe code bots to skim a spread off “dumb money” that turned out not to be there. Instead, they largely pass contracts back and forth among themselves all day. I won’t comment on what percentage of volume share I think they represent on platforms like Kalshi and Polymarket.

A rung, not a destination

But I have hope for the overall strategy. If you step back, the product looks less like a standalone idea than a step in a sequence. Line the instruments up and each is the previous one with a feature removed:

  • Puts and calls: continuous payoff, a real underlying, an open-ended tail.
  • The Plus Zone (a vertical): cap the tail, producing defined risk and reward with a ramp in between.
  • The “Plus Zone Minus” (a binary): remove the ramp for an all-or-nothing at one strike.
  • Event contracts: remove the numeric underlying entirely, leaving a yes/no on something with no price beneath it, like an election or the weather.

That’s the whole range, from the richest options instrument down to the barest event contract, each step shedding one thing.

To be fair…

None of this makes the product a bad one. The defined-risk structure is real. Your maximum loss is the premium you paid and it’s easy to understand. And if you want a capped, simple entry position on where the S&P closes today, it delivers exactly that. It’s clever, it’s legal, and it’s well-built.

I just don’t think there’s real demand for it. The experienced trader has better tools. The prediction market user can’t easily get in. The hedger and position trader were never the point. But if it’s a means to an end, then maybe it’ll all be worth it.

The CFTC’s Event Contract Challenge Isn’t Design—It’s Publicity

The CFTC’s initial event contract rules tell us what to expect moving forward.

The debate over event contracts pushes from both directions. One camp wants the CFTC to allow virtually anything and claim exclusive authority over all of it. The other wants whole categories walled off—sports, entertainment, and anything else that reads as gambling. My own goal is narrower and more practical: the broad adoption of event contracts by traditional finance.

A few weeks ago I went looking for a clean line that would screen out the most objectionable markets without strangling the legitimate ones, and I proposed a bona fide hedger test to draw it. The idea wasn’t intended to restrict the CFTC’s ability to claim jurisdiction, but rather to provide a defensible position from which any legitimate market could be included. It was a question of contract design: whether a counterparty could plausibly exist with exposure to the event independent of the contract itself.

The trouble is that any test like that is trivially gameable. Anything can be dressed as a hedge, especially when you consider that companies can manufacture scenarios they need to hedge simply to justify the basis for any theoretical market. How long before a casino claims it needs a roulette market to hedge its own table?

“Is there a hedger?” doesn’t separate a Treasury-yield contract from a roulette wheel, because someone is always hedging something. A test that admits everything isn’t a test. What survives is the intuition underneath it: a contract should derive from real economic substance to belong in serious markets. But that turns out to be a matter of judgment, not a rule you can write down and apply mechanically.

And the thing I was really chasing—whether Schwab and a pension fund would be comfortable putting this in front of clients—isn’t a property you can certify with a formula at all. Palatability isn’t measured. It’s judged.

The CFTC didn’t write a test either

That’s the lens that made the proposed rule click into place. The Commission had the chance to define a bright line for what counts as a legitimate event contract, and it declined. What it built instead is a multi-factor “public interest” analysis applied contract by contract, with a heavy thumb on how a market looks and how it would land with the public. The sports section makes it unmistakable. Contracts on final scores and season stats are fine. Contracts on player injuries are out.

The stated reason for the injury ban is that it creates “perverse incentives” to harm athletes—except that same incentive runs through the player performance contracts the rule explicitly allows, since an “under” on a player’s stat line also pays off when they’re hurt. The distinction isn’t falling out of a principle. It’s a judgment about what the public would find objectionable. Injuries read badly; an “under” doesn’t.

Managing perception is the point

A few months ago I’d have read that as a flaw. It’s a rule reaching for optics instead of a standard. But I get it now. It’s what I was trying to do, and the CFTC understands the ground realities more clearly than my test did. There is no clean standard. The category becomes legitimate by being palatable to the general public. That’s a precondition for the traditional finance adoption that follows. The CFTC is, in effect, running the category’s public relations as much as regulating its mechanics. It’s curating which markets the mainstream sees so the whole asset class reads as serious. Given where event contracts sit on their adoption curve, this is probably the right call for now.

Should we call it what it is?

Dressing a legitimacy judgment as a per-contract “public interest” finding invites the exact criticism that it’s arbitrary—because, as a test, it is. The Commission is managing the category’s reputation on the way to mainstream adoption, drawing and redrawing the line as public comfort shifts. That’s defensible, and it’s evolving. Today’s objectionable market is tomorrow’s normal, the way sports and elections already traveled from unthinkable to routine. A framework that admits it’s managing perception can adapt as perception changes. One that insists it’s applying a fixed test has to keep pretending the line was principled all along.

I should caveat that none of this is settled. It’s still a proposal and is open for comment through July. But the direction is clear, and I think it’s the right one. I don’t love the means, but they might be justified by the ends. I’ll be filing a comment to that effect.

My April comment letter.

Bringing Delta to Event Contracts: Consequitur Public Beta Now Available

I built something to fill the nagging gap between traditional options and event contracts.

On election night, Spencer Pratt led the second runoff spot in the Los Angeles mayor’s race by about eight points. The lead shrank a little with each new batch of ballots. The prediction market contract on whether he’d advance to November fell from the high 70s into the low 20s. And if advancement resolves against him, the contract on whether he’ll win the mayoralty in November won’t just reprice, it will end.

Nobody needs a tool to see that coming. Everyone knows that advancing in June is a precondition for winning in November. That part is obvious. But sitting underneath the obvious part is something more useful, and you can read it straight off the screen.

What two listed prices told you before the June election

Winning required advancing, so the November contract was really two things multiplied together: the chance he’d advance, and the chance he’d win if he did. Pull the two listed prices apart and the second piece falls out on its own. His win-if-advanced probability was just the November price divided by the advancement price. Advancement was trading around the high 70s before the primary. The outright-win contract was around a third. So the market was already saying that if he cleared June, the November price should jump to roughly the low 40s, and that if he didn’t, it should go to zero. Both numbers were priced in advance. The count only picks which one comes true.

That same number was also a hedge ratio. If you held the November outcome and wanted out of the advancement risk in particular, you could short the June contract in that proportion and keep a clean view on the runoff itself. As the count came in and his advancement odds slid, the ratio moved, and the hedge moved with it. One conditional probability was doing two jobs at once: the level the November price would snap to on advancement, and the ratio that offset one contract against the other. You could get it by dividing two quoted prices.

Unfortunately, it’s usually not that easy

You could only do any of that because the relationship was total and both contracts were listed. That is the rare corner. Picture a spectrum. At one end the sensitivity is essentially one: the first event all but determines the second, and the link is too obvious to need help. At the other end the events have nothing to do with each other, the sensitivity is zero, and there is nothing to model. Both ends are easy. Neither is where money gets left on the table.

The middle is where the opportunity lies. Most real relationships between events are partial price drivers. One event moves another by a meaningful amount without determining it. Had Pratt advanced, markets on whether stricter voter ID rules passed, or whether mail-in voting was restricted, would move his runoff odds. Not all the way, the way the advancement market did, but by a real amount. Those are the relationships that actually move a book, and they are the ones you cannot recover by dividing two prices. There is usually no listed contract for conditionals that pair them, and the relationship is not a clean nesting. Markets price whether a single event happens, continuously and in public. What nothing quotes is how one event moves another. The Pratt advancement/election pair was legible only because it was the exception.

What options have that event contracts don’t

In options, the reason you can manage a book at all is that you can take it apart. You know what each position is sensitive to. You can add those sensitivities up across the book. You can build a hedge that offsets the exposure you do not want. The machinery for that is the Greeks. The simplest one is delta: how much a position moves when the thing underneath it moves.

Binary event contracts have nothing like it. The continuous-price math the Greeks come from does not translate to a contract that settles at zero or one (setting aside certain scenarios with financial security underlyings). But the job delta does still needs doing: tell me what moves this position, and by how much, so I can offset it. The Pratt pair is that whole problem in miniature. When the relationship is total and both legs are listed, the answer is a division you can do in your head. Everywhere else, it’s invisible.

I’ve spent some time working out what the general version looks like, and I keep landing in the same place. For a standalone event, the closest thing to delta is the set of conditional relationships around it: the other events whose outcomes shift the world it resolves in, and by how much. I would not call it delta. It’s the event-contract analog—the same question delta answers—asked over events instead of a price. And it’s a cleaner object in one way and a rougher one in another. Cleaner, because a binary book moves in a straight line: there is no second-order curvature to chase, no gamma to manage. Rougher, because the number is only as good as your estimate of the relationship, and sharpening that estimate is exactly what the crowd is there to do. Map enough of those relationships across the positions you hold, and you have something that plays the role a risk book plays on a trading desk, expressed over events instead of prices.

Introducing Consequitur

Consequitur is the first working piece of that idea. The public beta is live now at consequitur.com. It’s free with no registration required. You can explore the graph, set your own estimates, and run scenarios without an account.

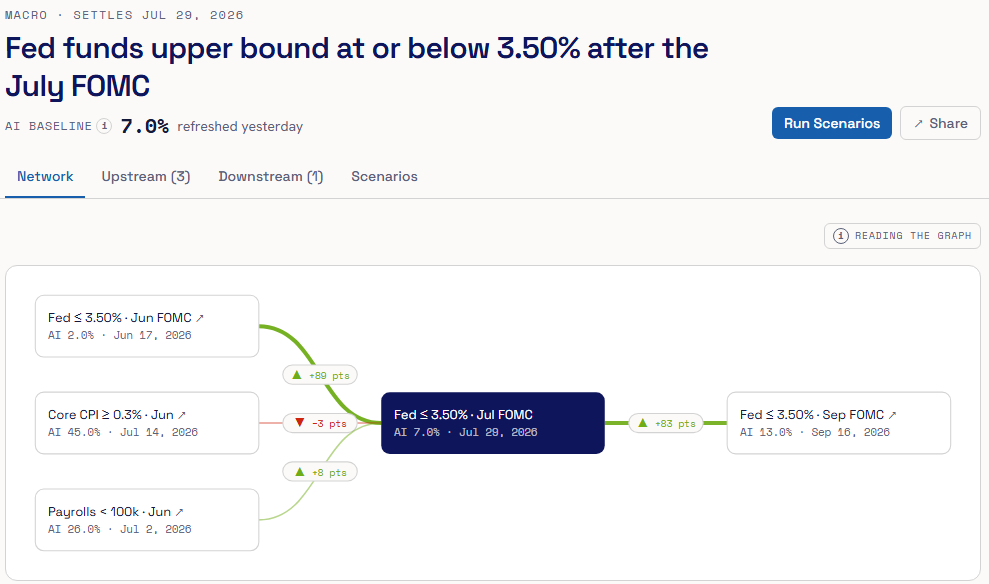
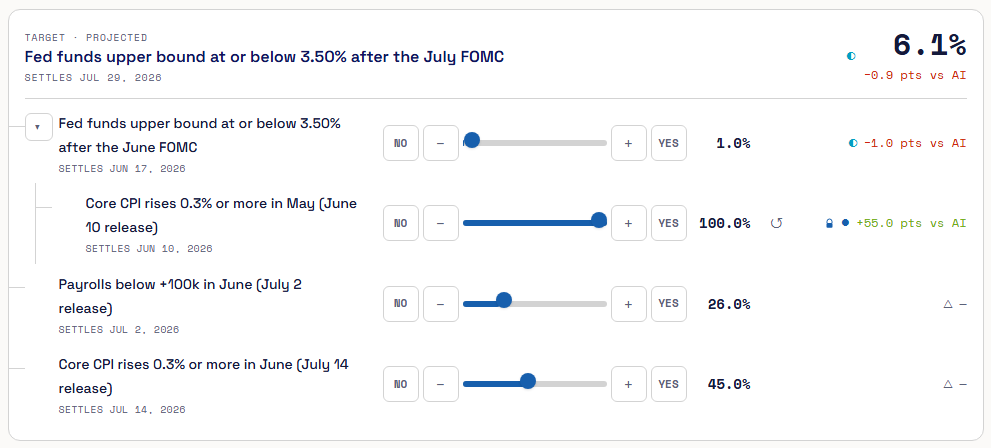
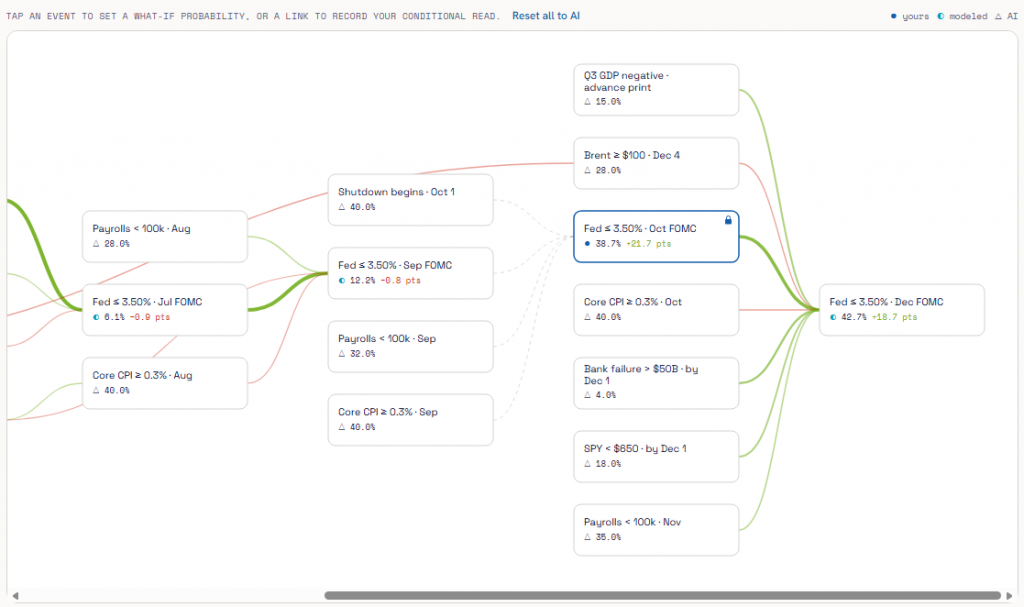
It’s a graph of real-world events and the relationships between them. Every event carries a live baseline probability, drawn from market prices where a market exists. Every link between two events carries a starting estimate of how strongly one bears on the other. Where you disagree with a link, you set your own number. Then you run the what-if: adjust the marginal probabilities of events in the network and watch the implied probabilities move across everything connected to them.

The beta opens on a single anchor, the question most likely to move every other market this year: does the Fed deliver at least one cut in 2026? Around it sits a graph of inflation prints, labor data, energy, and geopolitics. That includes the cascade I mentioned earlier: a ceasefire holding or breaking, feeding oil, feeding inflation, feeding the Fed. Every link in that chain is a partial price driver. None of them is obvious, none is deliberately priced anywhere, and all of them are regularly refreshed. Pin the ceasefire to “collapsed” and watch the pressure travel down the chain to the rate decision. That is the everywhere version of what you got to watch happen once, in the open, with Pratt.

The roadmap

This beta is a down payment on a broader vision of tools that anyone can use to better manage a portfolio of event contracts. It will include more interactivity to support setting position quantities in order to explore how various events are likely to impact position and portfolio value. It will make it easier to identify hedging opportunities that lower risk, including ones that wouldn’t be obvious otherwise. And because those hedges fall out of the sensitivities you declare, the same machinery shows you where a contract is priced out of step with your view—the event contract version of an option looking cheap or rich against your read on volatility. It will provide better insight into the systematic and unsystematic risk components of event prices so you can easily understand how much probability is independent vs. sensitive to other tracked events.

None of that ships today. What is live is the Fed graph, your own estimates, and what-if scenarios. One anchor, free, no signup. The data layer is step one. The workflow on top of it is what comes next, and I would rather build it in the open than oversell it.

Building in the open includes being explicit about the methodology. If you want the precise version of what each number means, how the engine moves a shock through the graph, and where the model breaks, I published a technical document with the launch. It’s a systems document, not a sales pitch. The limitations section is the longest part on purpose.

Try it

If you trade these markets, or you just want to see what it looks like to put real numbers on the relationships between events instead of carrying them around in your head, the Fed graph is the place to start. Pin an event, break the chain, and watch what moves. It’s at consequitur.com.

Consequitur is a sister product to Qwidgets, which I built for comparing and trading contracts across exchanges. Qwidgets is about the contracts. Consequitur is about the relationships between the events behind them. For now they’re independent (and separate from the option market products) but we’ll see where the road takes us.

Thanks in advance for any feedback.

Quantcha Launches Consequitur Beta: Free Cross-Event Sensitivity Analytics for Prediction Markets

Quantcha, the options trading analytics platform that has served thousands of investors since 2014, today announced the public beta of Consequitur—a free tool that lets anyone map how real-world events move each other and model what a shift in one event does to the probabilities of the others.

The beta is available now at consequitur.com. No account or signup is required to explore the graph, set your own estimates, or run what-if scenarios.

Prediction markets already price levels—the probability that any single event resolves YES—continuously and in public. What no market shows you is the conditionals: how much one event’s probability should move when another resolves. That gap is what Consequitur is built to work in. Every event arrives with a live AI baseline, informed by market prices where a market exists—Kalshi, Polymarket, and more—and every link between two events carries a starting estimate of how strongly one bears on the other. Where you disagree, you set your own. Then you run the what-if: hold an event at YES or NO and watch the implied probabilities ripple across everything connected to it.

“Markets have gotten remarkably good at pricing whether any single event happens,” said Ed Kaim, Founder of Quantcha. “What nothing prices is how events move each other. If the ceasefire collapses, what happens to oil? If oil spikes, what does the next inflation print look like? If inflation surprises, what does the Fed do? Every desk carries a mental model of that cascade, but it lives in heads and hallway conversations—there’s nowhere to put real numbers on it and see what it implies. In options, your edge comes from estimating whether implied volatility is priced correctly. In prediction markets, it comes from estimating whether the probability itself is correct. Consequitur extends that one more step: estimating whether the relationship between two probabilities is correct—then showing what that implies for every connected event. Map enough of those relationships across a book of positions and you have a sensitivity layer for event exposure—the role a risk book plays on a trading desk, but over events instead of prices. That’s the direction we’re building toward.”

A Maturing Market’s Unpriced Layer

Prediction markets have scaled from niche curiosity to mainstream financial instruments, with regulated exchanges, institutional market makers, and broadcast partnerships putting implied probabilities in front of millions of investors. The analytical layer on top of those markets is maturing quickly—but it is almost entirely within-market: charting, order books, and portfolio tools for contracts the exchanges already list. The structure connecting those contracts—how a move in one event reprices the next—is something no tool has let an individual work with directly.

The beta launches with a single anchor graph built on the question most likely to move every other market this year: does the Fed deliver at least one rate cut in 2026? The graph spans 21 events and 22 dependencies covering inflation prints, labor data, energy and geopolitics—including the ceasefire-to-oil-to-inflation-to-Fed transmission chain—and cross-domain catalysts.

Key Features

  • The Event Graph, with Live AI Baselines: A directed graph of real-world events where each node carries a live AI probability baseline, informed by market prices where a market exists—Kalshi, Polymarket, and more. It’s the starting point you adjust, not a fixed answer.
  • Your Own Estimates: Set your own view on any link between events—no account, no signup. Each estimate is recorded as the shift it implies against the baseline, so it keeps working as the underlying markets move.
  • What-If Scenarios: Hold one or more events at YES or NO and watch the implied probabilities of every connected event move in real time.
  • Open Methodology: A live methodology page documents the model in the open; review the in-depth technical whitepaper.
  • Free and Link-Shareable: Every graph view and scenario travels via URL. Share a what-if the way you’d share a chart layout—no paywall, no gating.

The Roadmap

The public beta is deliberately scoped: one anchor graph, free, no signup. The roadmap is where the larger thesis lives. Structurally, the graph is a sensitivity surface for a book of event-contract positions—the event-space counterpart of the risk book a trading desk keeps, mapping what moves a position and by how much across events rather than prices. In the domains where no price process exists to derive such a thing—politics, policy, geopolitics—there is today no established way to compute one at all. Nearer term, the roadmap adds further anchor graphs and synthetic market discovery: inferring implied probabilities for events no exchange currently lists from the conditional structure around them. All of this is future work; what is live today is the Fed graph, your own estimates, and what-if Scenarios.

Consequitur is a sister product to Qwidgets for Prediction Markets, Quantcha’s within-market analytics platform: Qwidgets covers comparing and trading contracts across exchanges, while Consequitur covers the relationships between the events themselves.

Explore the graph, set your estimates, and model a what-if at www.consequitur.com.

Kalshi’s American Power Index Is [Hopefully] the Start of Something Bigger

KPOW is the foundation Kalshi needs to attract options investors to political markets

On May 28, Kalshi launched the American Power Index (KPOW), a composite running from +50D for maximum Democratic control to +50R for maximum Republican control. It does so by blending 75% from Kalshi market signals on future House, Senate, and Presidential outcomes with 25% current ground truth on seat counts and offices held.

There was immediate appreciation for the nature of an index that quantifies the political outlook for the US. It’s a great accent for news stories discussing the overall political dynamic. But I think it’s actually way more. Played correctly, it’s a mechanism that sets them up to dominate a whole class of investing before the traditional finance world has even joined the game.

Trading the index

KPOW is a self-published composite index, which puts it in the same product category as the S&P 500 or the VIX. Indexes are intellectual property. Once an index has methodology, gravity, and derivatives quoting against it, the publisher owns something durable that the contracts above it inherit value from. This opens up the playbook for ways to reach a mass audience of legitimate investors through multiple strategies. I don’t know which ones will work, but being first gives them the positioning and the time to figure it out before anyone else.

On a related note, BTCPERP launched the day after KPOW. It’s the first US-regulated perpetual futures contract. It followed a separate regulatory pathway and is for a different audience, but the two launches together are evidence that Kalshi is behaving like a CFTC-regulated derivatives venue building serious finance inroads and not the gambling-obsessed caricature portrayed in media.

The relevant question on KPOW is not whether Kalshi will list more political contracts, but rather what the index can support and what gets built on that foundation.

The first product: term series binaries

The mechanically simplest move is presumably the near-term one. Kalshi can establish a term series of binary event contracts on the index value—strikes at +0, +10R, +20R, +25D, and so on—across monthly expirations through the midterm cycle plus an Election Day series. A trader expresses “KPOW above +0D on November 9” or “KPOW between +10R and +25R on January 1” in a single ticket, on the same venue, with the same account.

Quick disclosure: I have requested but not yet received access to the methodology whitepaper. I have some concerns regarding the usefulness of this index based on the limited history that’s available. The Republicans were in a very strong position after the 2024 election, but their peak was only +7.9R. If the practical range for KPOW is going to be narrow, like +10D to +10R, then it will be less elegant to layer securities over.

The traditional finance crossover

I argued in Eleven Years Circling Prediction Markets that closed-end funds accessible on traditional brokerage accounts could be an elegant way to drive a critical mass of demand from traditional retail and institutional investors. The idea was that someone needed to provide the missing piece of mucking around in the granular and tedious prediction market contracts to distill a class of risk into a single, more accessible asset.

The alternative that I didn’t spend time on—which I wish I had at least mentioned in hindsight—was the idea of Kalshi themselves stepping in to ship an index like KPOW. Now ETFs can be formed in various ways and traded on the millions of brokerage accounts these investors already hold.

There’s already a precedent for this as multiple ETFs that track party outcomes after the election are already available with more on the way. Their specific utility may be less valuable if replaced by a broader KPOW ETF. We’ll have to see how it shakes out.

Touching on something more interesting

Any of those single-instrument products is a clean way to express a tactical view on political control. The bigger opportunity is opening Kalshi’s markets to the equity options crowd. Not because their income strategies translate cleanly—the structural seller premium that makes covered calls and credit spreads work in options markets requires hedger flow that prediction markets haven’t yet attracted. But touch markets give that audience the contract shapes they recognize: calendar spreads, term-structure trades, path-dependent positions. Showing the shape first is what brings the people who eventually develop the demand.

The contract shape is touch markets. Unlike terminal measurement markets like “Will KPOW trade above +10R on November 1?”, touch markets ask “Will KPOW trade above +10R by November 1?”. The difference is the early settlement potential that provides a clean hedge structure across expirations on the same barrier. It also enforces a coherent pricing surface across the term grid that can be used for volatility modeling in ways terminal binaries can’t support.

A simple example

Say KPOW is at +5R and touch markets exist at the 0 barrier with monthly expirations. The market is asking “will KPOW touch 0 by [date]?” Prices follow the monotonicity of touch probability—longer windows price higher because there’s more time for the barrier to be reached. With R holding the current lead, the curve might look something like $0.15 by July, $0.20 by August, $0.25 by September, and so on out to $0.40 by December.

An investor with an R view (KPOW stays positive) structures a calendar. Buy Yes touch-by-Dec at $0.40 as the long-run hedge that pays if the R view is wrong over the full horizon. Sell Yes touch-by-July at $0.15 as the near-term premium against the same view. Net debit: $0.25.

That $0.25 is the maximum loss on the structure. If KPOW touches 0 immediately—before July 1—both contracts trigger simultaneously because they share a barrier. The long Dec position pays out $1 and the short July position pays out $1, netting to zero on the touch event itself. The trader is left with only the initial $0.25 debit. The cross-term hedge worked: the long far-month protected the short near-month against the trigger they share.

If R holds through July, the short expires worthless and the trader keeps the $0.15 premium. So they roll by selling Yes touch-by-Aug at $0.20. Then repeat if R holds through August, rolling into September at $0.25, October at $0.30, November at $0.35. Each successful roll collects premium against the same long Dec hedge. The asymmetric structure caps downside at the initial $0.25 debit and lets upside accumulate through the roll.

If R holds all the way through to December expiry and no touch ever happens, the long Dec also expires worthless. The trader’s P&L is the sum of all premiums collected minus the cost of the long: $0.15 + $0.20 + $0.25 + $0.30 + $0.35 minus $0.40, or +$0.85. That’s the best case and much better than if they had simply bought No on Dec for $0.60 ($0.40 profit).

If touch happens mid-roll—say, between October and November—the trader has already collected premium on the expired July, August, and September contracts ($0.60), plus the October premium ($0.30). When the touch triggers, the short October pays out $1 and the long Dec also pays out $1, netting zero on the trigger event itself. Final P&L: -$0.40 (Dec) + $0.15 + $0.20 + $0.25 + $0.30 (premiums) = +$0.50, plus the wash on the trigger. Still positive.

Two practical notes. First, if the term-structure pricing inverts—the long-dated premium too rich relative to the monthly rolls to justify the structure—you flip directions: sell the long-dated touch and buy the short-dated as the hedge. The structure follows the pricing surface.

Second, this calendar only works because touch markets share a single trigger event across all expirations at the same barrier. Trying to construct the same trade on terminal binaries doesn’t work—a “KPOW > 0 on July 1” contract and a “KPOW > 0 on December 1” contract have independent settlement points, so a brief cross below zero between those dates doesn’t symmetrically affect both contracts. The cross-term hedging is the load-bearing feature of the touch market design, and it’s why a varied strike and term ladder lets traders extract real volatility surface measurements across contract pairs.

What ships next determines whether Kalshi owns the category

Term series binaries on KPOW are the easy ship. They’re the first real product on the foundation and would cover the tactical audience cleanly.

Touch markets are the harder ship and the more interesting destination. The methodology is heavier (every tick matters because every tick can trigger settlement), the strike-and-term ladder needs active management against the narrower-than-nominal operating range, and the calibration question above gets more acute. But they’re what brings the options crowd in, what makes the cross-term hedging structures work, and what gives the pricing surface enough geometry to support actual derivative analytics.

The competitive question is who else moves before Kalshi finishes. Polymarket has the infrastructure and political market density to publish a competing composite, but their recent partnerships (Serie A, La Liga, MLS) suggest a sports-first posture rather than diversification across topics like US politics. Independent index publishers have methodologies but haven’t commercialized at scale. The window where Kalshi can establish gravity around KPOW—the same gravity that keeps the S&P 500 the S&P 500 even as the venues licensing it change—is open right now and probably closes ahead of midterms.

What KPOW signals is that political investment is becoming a real category. Not “gambling on elections.” Not “sports betting with extra steps.” An asset class with continuous exposure, a term structure, hedging mechanics that work, and eventually a brokerage wrapper that lets a 401k holder express a view on which direction the country is heading. Kalshi published the foundation last week. What they ship on top of it may decide whether they own the category or share it.

Standardization or Bust: Why Event Contracts Need a Consolidated Clearer

A builder’s case for standardizing the layer everyone is fighting over.

The CFTC is about to decide which event contracts it will treat as derivatives and which it will leave to state gambling regulators. The visible fight is over contracts traditionally managed by sportsbooks and other venues, but the consequences of that decision reach much further than sports gambling.

How do the sportsbooks feel?

Unsurprisingly, the largest sportsbooks don’t want competition from Kalshi, Polymarket, and the others. They’ve invested a lot to get where they are, and part of that is the commitment to hand over a huge portion of their revenue in state taxes.

For example, if a sportsbook has a 51% gross margin in NY—meaning they have $51 left after expenses for every $100 of revenue—how much do you think they take home in earnings?

That was a trick question. NY has a 51% revenue tax, so the answer is zero. NY (and Rhode Island and New Hampshire) take most of what you make off the top. It’s not that bad everywhere, but the blended national is around 25% of revenue. How do you compete with someone who sidesteps that tax entirely by offering the same product through a different regulatory modality?

You don’t. If the CFTC prevails and the competition is inevitable, the sportsbooks pivot to the exchange model because the economics give them no choice. Sporttrade already did. Others will follow.

But that’s only going to impact sports gambling, right?

Maybe at first. But I’m less focused on that side of the fight. I’m more concerned with the implications for event contracts in traditional finance—or more specifically, clearing.

Right now, every prediction market and event contract exchange clears for itself. That means they define what contracts are available and keep track of who holds what. You can’t trade those contracts outside of their US exchanges, and there’s no enforcement of standardization. You can’t net positions across venues to free up collateral, and the settlement definitions can vary enough that the “same” event resolves differently on different exchanges.

The way I see it, there are three outcomes for the future of event contract clearing, and they hinge on the CFTC gambling showdown.

Scenario 1: The CFTC regulates all event contracts

The first scenario is the one I’ve been outlining—the CFTC retains dominion over all event contracts and the mass pivot of gambling venues into exchanges actually happens. The space becomes substantially fragmented and everyone fights to protect their own walled garden. This likely leads into a period of specialization and consolidation from which a handful of major players emerge.

Liquidity providers have to allocate capital across venues, so they specialize on venues and domains and overall depth thins out—wider spreads, fewer markets, or both. And the same event listed on multiple venues with different settlement criteria is exactly the basis risk problem from a moment ago, multiplied across every event that matters. The category becomes harder to use precisely where it should be easiest.

Scenario 2: No near-term clarity

There’s also a no-op case where the regulatory framework doesn’t anchor. The CFTC might not decide for a long time, or it might make decisions that don’t survive the next administration, or it might be overridden by courts or Congress. These might seem like significantly different paths, but I think they lead to the same outcome.

Infrastructure investment requires regulatory clarity that nobody can commit to. Each venue keeps building its own clearer, walled garden incentives win by default, and the cross-venue fragmentation gets baked in further as a handful of large players entrench. This is probably the most likely outcome from where we sit today. The CFTC has more pressing concerns than event contract structure, and the political fights around sports may consume bandwidth without resolving the underlying question.

Scenario 3: The CFTC draws a principled line

The third scenario is the one I’d pick if I could. The CFTC draws a principled line based on economic utility rather than category. Contracts pass a bona fide hedger test—there’s a real commercial counterparty with exposure to the event independent of the prediction market—or they don’t. Pure speculation products get ceded to whatever framework actually fits them. The principle is universal, and applied consistently it sorts the category clean.

When that happens, the conditions for shared infrastructure exist. The standardizable subset is coherent, and the constituencies that benefit from consolidation actually have something to push for.

The brokerages are the first group. Schwab, Fidelity, and the rest run their futures and options operations on the assumption that the instrument is a standard and the venue is interchangeable. They aren’t going to be happy distributing event contracts where every venue’s product is its own thing. Two major futures exchanges with overlapping contracts is already pushing it, so ten venues each running their own “Fed cuts in July” would be a different magnitude of problem.

There’s also a categorical issue underneath the structural one. Legit retail brokerages have stayed firmly on the financial products side of the line for decades and aren’t going to distribute something that reads as gambling-adjacent to their customer base. They’ve told me so directly. The principled line in Scenario 3 is what makes the category palatable for their distribution in the first place. As real liquidity develops, I expect they’ll demand fungibility as the price of integrating at scale.

The liquidity providers are the other group. A market maker today runs a fragmented book with collateral on every venue, no netting across, no defined relationships between contracts that obviously move together. A standardized set fixes both halves: capital scales across the market, and exposure can be hedged against the structure of the market rather than against disconnected line items.

My suggested solution will not be a surprise for options traders: a consolidated clearer.

What consolidated clearing did for options

It’s not a theoretical concept. The options world built one in the early 1970s.

The Options Clearing Corporation sits behind every listed equity option in the US. It issues the contracts, guarantees every trade, and—the part that matters here—owns the standardized definitions. A given call is the same instrument wherever you bought it, because it’s the same contract cleared in the same place. It’s fungible.

This opens up a world of opportunity to trade across venues, net positions against each other, and simplify all the layers that sit on top. On the other hand, it commoditizes what the existing prediction markets do, meaning that they’d be limited to competing on things like execution, fees, and tools. They may not like that.

Where I land

I’ll say plainly where I land. I build in this space and I’m not neutral about it. I want standardization to make my life easier, but I also sincerely believe it will be better for the industry.

Last week I wrote about this category’s deeper demand problem, that it needs a real counterparty to the hedgers, and that a discretionary closed-end fund could package that exposure for retail. That’s not a competing argument. That was about demand, this is about plumbing. A fund putting retail capital to work across these markets is exactly the kind of participant that needs standardized contracts to operate. Demand gives the market a reason to exist; standardization is what makes it work once it does.

The case against me

The case against me has one sharp version worth admitting. Right now an exchange can list a market on almost anything in a day or two—a breaking story, an obscure data print, a one-off cultural question—because the CFTC’s self-certification regime lets new contracts go live with minimal review.

Standardization is the opposite: agreed definitions, agreed resolution sources, an onboarding process. You’d be trading away the thing this category is genuinely best at—speed.

My answer is that it was never all-or-nothing. The standardizable core can clear on shared rails while the long tail of spin-it-up-overnight markets stays as fast and proprietary as it is now. You can standardize where it pays and still keep the fast lane open.

What I’m watching

The Clearing Company is a live bet that the shared clearer outcome is coming. The CFTC’s handling of sports is the test of whether it’s willing to draw a principled line. The liquidity providers and brokerages are the real representatives of supply and demand that need to be won over.

I’m not a fan of hyperbole, but at this point I think the long-term event contract success is standardization or bust.

Eleven Years Circling Prediction Markets

A founder’s notes on eleven years of being early—and what finally changed.

I’ve been stalking prediction markets for eleven years.

The earliest thread I found is a 2015 email where I pitched one of Quantcha’s financial engineering advisors on the idea of “sports options”. This was well before the industry co-opted the term “prediction markets” from academia, and I was coming at it from a portfolio-management-through-derivatives perspective. I didn’t even think of what I was describing as a prediction market. I thought of it as a vehicle for sportsbooks to hedge their outcome risk and offer customers more sophisticated products.

I took the idea to a few BD-minded founders, and had long, productive calls with others who had launched their own exotic-derivatives ventures. In every version of the conversation, the opportunity hinged on the same thing: liquidity. It would not work unless I could bring in participants willing to buy and sell—ideally both—in size.

Nobody was ready

Another lesson came out of those calls: you cannot build this on speculators. A market like this only works when both sides have a real reason to be there—when at least one of them is moving genuine risk, not just taking a view.

The sportsbook version had a flaw I couldn’t design around. It seemed impossible that sports betting would clear at the federal level, so the product had to stand on its own as genuine risk transfer. Unfortunately, a sportsbook laying its book off onto a crowd that just wants the other result isn’t moving risk to a hedger; it’s finding more speculators. It’s gambling with extra steps, and I could never draw the line cleanly.

I went looking for cleaner ground—places where the risk being transferred was unambiguous. In 2018 and 2019 I tried approaching casinos and tribes on a syndicated market-making system that would pool liquidity across venues. I pitched insurers on a model for socializing weather risk—trading out of exposure to temperature and other weather phenomena. When the lockdowns hit in 2020, I angled toward state governments with exchanges where tourism-dependent businesses could hedge against the next shutdown (or even just underperformance).

The conversations were warm, but nobody moved. The conditions weren’t there—regulatory, institutional, or otherwise—and nothing on the horizon looked strong enough to change that. I wasn’t wandering between those industries at random. I was running one test in each of them—is there a counterparty here with a real risk to move?—and getting the same lukewarm answer every time.

Proving the concept

I did build something, though. When COVID locked down Washington State, I had about 20 hours a week back—time I would otherwise have spent coaching youth teams and running school clubs—and I put it into the infrastructure as a passion project. I built it generic on purpose: a core platform (exchange, clearing, custody, arbiter) with a thin adapter layer on top, so the same engine could be quickly adapted for sports, insurance, public statistics, or whatever vertical came next.

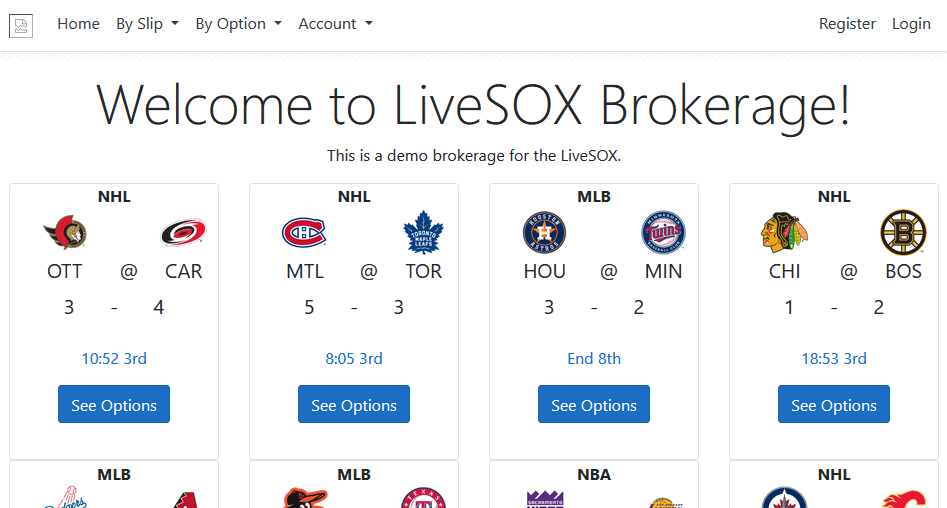
Live Sports Options Exchange (livesox.com at the time) became the first reference implementation. It was a fun concept to build for and a good way to demo. It had a brokerage frontend, an arbiter service, and two bots: one took out simple price arbitrage, and the other made markets by inferring a rough distribution from published moneyline and over/under odds. The currency layer was pluggable, so the whole thing could run end to end on test credits while the capital and regulatory structure got worked out separately.

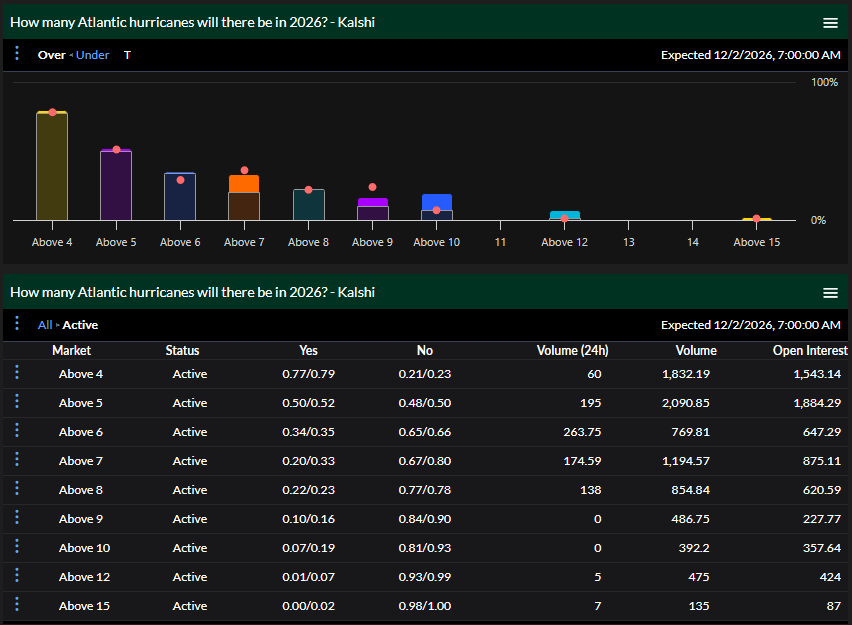
One benefit to the implementation was that it gave me a complete view of what building and operating a system like this would require. But, perhaps even more valuable, it also let me dogfood the actual user experience beyond the software. That was eye-opening, because I started to have real doubts about the end-user use case. It made sense why someone would want to take the “over 40.5 in Sunday’s Seahawks game,” but it was much less clear that it would translate into enthusiasm for the “over 4.5 Atlantic hurricanes this year.”

The great thing about having the sunk cost of operating Quantcha is that it’s easy to spin up these prospective ventures and let them coast in case something catches fire. They never have to die…until the domains come up for renewal.

Someone actually pulled it off

Meanwhile, companies like Kalshi and Polymarket broke through. It’s easy to be impressed with what they’ve done as a casual observer, but I remember looking at the daunting requirements to solve for the regulation and other legal issues at the time and deeming it impossible. It’s now as easy to set up and trade event contracts on one of them in the US as it is to open a traditional brokerage account and trade options. Actually, it may be even easier given options-approval overhead.

They’re making inroads—or at least establishing policy—to appeal to businesses looking to offload risk. Kalshi has incentive programs for sportsbooks and sports contract insurers that may already be playing a meaningful role in the transactions that dominate its volume. These are legitimate derisking scenarios where those companies can lose on their Kalshi trades and still come out better overall given the hedging purpose those positions served.

What I’m not sure they’ve solved is the fundamental end user problem: can they get investors to trade event contracts? I don’t have any special insight here, but the conventional wisdom is that their retail flow is predominantly gambling (or, more generously, “speculating”). Without a critical mass of traditional investors onboard, it will be tough to attract other industries looking to derisk.

Look out for strong headwinds

Consider Kalshi’s market for “How many Atlantic hurricanes will there be in 2026?” It’s the middle of May, and the open interest is 6,667 across nine threshold markets. That represents under $7,000 against the potential for tens of billions of dollars in damage. There is obviously not enough interest on both sides for this market to have a meaningful impact—yet.

Getting demand for Over is easy. Insurers would love to offload risk if they can get a better expected value for their whole book. They’re probably not involved yet because there’s no meaningful Under demand. That demand would have to coalesce from the broader market.

My gut feeling is that investors, especially retail investors, do not want to trade these individual contracts. They would be interested in the exposure at the right price, but they also understand the kind of research and monitoring commitment they’d be making by getting involved.

Funding the future of prediction markets

If I’m right about that, then the best solution is a Closed-End Fund. And I don’t mean the proposed ETFs that wrap a specific event contract—I mean a discretionary fund managed for exposure to the different kinds of risk that prediction markets (and other modalities) help quantify. There are a lot of edges to smooth out, but this approach would give a retail investor the easiest way to express a view—“I think this season is going to be less risky than the premium implies”—and have that ultimately connect to the insurer looking to offload the risk.

For a long time, the honest answer to all of this was “not yet”. No venue, no liquidity, no regulatory ground to stand on. The thing I kept circling couldn’t actually succeed, so I didn’t build it. That part is over. What’s left is no longer an impossible problem, just a hard one: find the demand that sits across from the insurer and give an ordinary investor a reasonable way to supply it. A discretionary fund is one shape that bridge could take. There are surely others. I don’t know yet who builds it or how. I do know that, for the first time in eleven years, it’s a problem worth trying to solve rather than one to wait out.

If you’re an investor, insurer, or operator thinking about this space, I’d love to hear how you see the demand-side challenge. Drop a comment or DM—happy to compare notes.

Dead Cap Space: Why Polymarket Favorites Are Subtly Cheaper Than They Should Be

If you’ve followed the NFL offseason, you know dead cap. It’s the salary cap charge a team takes for a player who isn’t on the roster anymore—bonus money paid out years earlier, amortized across the original contract, still eating the budget long after the player was cut or traded. The Falcons carried over $40 million in dead cap going into 2024 after the Matt Ryan and Julio Jones era. The Broncos took a similar hit after the Russell Wilson trade. Dead cap doesn’t win games. It doesn’t put anyone on the field. It just sits there, taking up budget that could have been renegotiated to a current starter.

Prediction markets have it too. Specifically, negative risk markets on Polymarket do. It’s the minimum allocation the underlying mechanics require for all active markets, even those that are all but eliminated.

The conservation budget

Polymarket’s NegRisk adapter pegs the sum of every Yes price in a multi-outcome market to $1. Every team gets a slice. The slices add up to a whole. The peg isn’t enforced by Polymarket itself—it’s enforced by arbitrageurs. Whenever the sum of prices you can buy all at drifts above $1, an arbitrageur can split $1 into a complete set of Yes contracts (one for every team in the field) and sell each one at market, collecting more than the $1 they put in. When the sum drifts below $1, the reverse: buy a complete set for less than $1 and merge it back into $1. Arbitrageurs run this loop constantly, and the peg stays tight in real time.

For our purposes, think of it as a salary cap. Polymarket has a fixed $1 budget for the World Cup market, and every team’s price has to fit under that cap. If France ought to win 30% of the time, France’s Yes should trade around $0.30. Argentina around $0.20. And so on, down through the field.

Now here’s where dead cap comes in.

The longshot floor

The lowest price you can trade the World Cup on Polymarket is $0.001. One tenth of one cent. It’s a mechanical limit imposed by the platform—you cannot bid or offer a contract below it. So the cheapest a deep longshot can possibly trade is the tick floor.

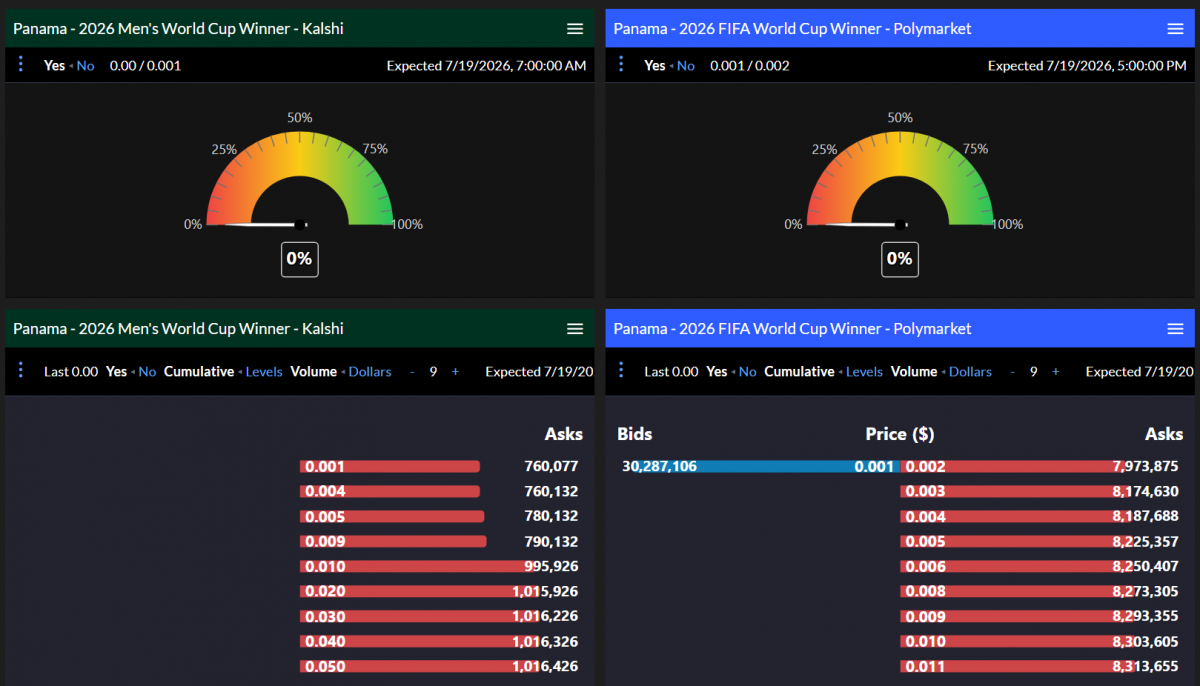
Most deep longshots in a 48-team World Cup field are nowhere near that price as a fair value. Panama’s true probability of winning the World Cup isn’t 0.1%. It’s something well below—pick your number, maybe 0.01%, maybe lower. But you can’t trade Panama Yes at $0.0001. You’re stuck at the $0.001 floor minimum. So Panama Yes is structurally overpriced relative to its true probability by something like an order of magnitude.

That overpricing—the gap between where the contract trades and where it ought to trade—is dead cap. Budget allocated to an outcome that effectively can’t happen, eating the $1 cap without contributing anything real to the market’s price discovery.

The wall

The tick floor sets the lower bound, but it doesn’t fully explain why deep longshots routinely trade right at it. A mechanical floor at $0.001 could still allow sparse trading. What you see on Polymarket instead is a wall: tens of millions of contracts deep on the bid side for outcomes like Panama, with matching depth on the ask one tick up. Not a thin floor. A wall.

Polymarket’s maker rebate program is a tempting first explanation. The platform pays liquidity providers to post depth, and posting at the tick floor on a longshot is a low-effort, high-volume way to harvest those rebates. But the rebate pool allocated to a market like Panama is on the order of single-digit dollars per day. That’s nowhere near enough to incentivize tens of millions of contracts of standing depth. Whatever’s holding the wall up, the rebate program is at most a small contributor.

It’s also worth ruling out the clean-sounding story that the wall is MMs scrambling for longshot Yes inventory. The MM that mints a complete set is usually doing so to satisfy favorite-side demand—someone wants France or Argentina, the MM mints $1 into a complete set and sells off the favorite Yes to fill that demand. The longshot Yes contracts left in inventory afterward are surplus the MM would happily sell, not scarcity the MM is hunting. So if anything, the natural MM posture on longshots is on the offer side, not the bid side.

Which leaves the bid wall itself as a genuine puzzle. The bids on Panama are sized at roughly 6x the asks at $0.002. If everyone has a Panama surplus worth nothing, why not dump them all off for whatever you can get? Maybe it’s not worth crossing the spread. But then how did the bids get there to begin with? These are sincere questions I still haven’t found a good explanation for. Whoever is absorbing the longshot supply at the floor is doing it for reasons I can’t cleanly account for from the outside.

What I can say is that the empirical pattern holds regardless. Longshot Yes prices on Polymarket NegRisk markets sit at or near the tick floor for the duration of the market, with deep depth on both sides of the spread. The exact composition of who’s bidding and why is harder to pin down. The consequence is what we can read straight off the order book.

The dead cap tax

So we have a $1 cap, a sustained longshot premium that sits there regardless of mechanism, and conservation arithmetic to resolve. The math is straightforward but the precise number depends on which price you measure. If 18 deep longshots in a 48-team World Cup market each carry a midpoint near $0.0015—a $0.001 bid against a $0.002 ask—the cumulative dead cap is around $0.027, roughly 2.7% of the $1 budget consumed by outcomes that effectively can’t happen. At the bid the figure is closer to $0.018; at the ask, $0.036. Pick whichever reference price reflects what you’d actually transact at.

Distributed across the handful of meaningful favorites, you end up with each favorite trading somewhere in the 50 to 70 basis point range below its true probability. That’s the dead cap tax. France, Brazil, Argentina, England and every realistic contender is quietly discounted—likely in proportion to their odds—because Panama, Ghana, and the rest of the deep field are quietly overpriced.

This is real edge, but it’s small edge. We’re not talking about a hot tip. We’re talking about a structural feature of Polymarket’s market design that gives the favorite-side bettor a small, persistent, structurally-explained discount. On a $100 bet on France, the dead cap tax might be worth $0.50 to $0.70 of expected value. You’re not going to retire on it. But you’re collecting it whether you know about it or not.

One way the analogy bends: unlike NFL dead cap, the prediction market version isn’t permanent. As deep longshots get eliminated from the field through group stages and knockout rounds, their contracts settle at zero and their contribution to the budget vanishes. The favorite discount compresses through the tournament. By the time the field narrows to two teams in the final, there’s no dead cap left to redistribute. The discount is at its largest when the field is widest. If you want to capture the full structural edge, you’re betting favorites early in the tournament, not late. However, any edge early in the tournament probably doesn’t make up for the lack of APY on your positions.

Why Kalshi doesn’t have this specific tax

Kalshi doesn’t have a NegRisk-style atomic split-and-merge across the outcomes of a multi-team market, so there’s no $1 conservation peg holding the basket together. Each contract pair is its own market with its own collateral logic. Kalshi does have collateral return mechanics—settlement releases collateral, and some series markets recognize mutual exclusivity for collateral purposes—but none of those create a hard peg that has to redistribute mispricing across the basket the way NegRisk does. So the specific dead cap tax described here doesn’t operate on Kalshi.

That’s not to say Kalshi favorites are priced fairly. Kalshi has its own distortions, most notably the overround on multi-outcome series, which often pushes favorite asks well above their true probabilities. And that’s generally more than the dead cap pushes Polymarket favorites below them. Different architectures, different distortions, opposite directions. The point of this piece isn’t that Kalshi is fairer than Polymarket. It’s that Polymarket’s specific architecture produces a specific, mechanical, persistent favorite discount that’s identifiable in the order book and capturable in expected value.

Dead cap is what Polymarket pays for the elegance of atomic split-and-merge—the same mechanism that gives the platform its tight conservation peg, its cross-outcome arbitrage, and its capital efficiency. The favorite-side discount is the giveback. The longshot mispricing is the cost. Both are structural, both are visible in the order book, and neither is going anywhere as long as the architecture stays this way.

If you bet favorites on Polymarket, you’re collecting the giveback whether you meant to or not—paid for, in part, by the longshot overpricing the same architecture produces. Not big enough to retire on. Real enough to know about.

How the Seahawks Exposed Polymarket’s Long-Term Problem

Following up on Tuesday’s cross-exchange piece where my love for the Seahawks resulted in a rare and uncharacteristic mistake.

I felt pretty good about Tuesday’s cross-exchange arbitrage article, but I still couldn’t sleep. I made an assertion—sort of a handwave for an otherwise solid model—that the reason the Seahawks were trading at a discount on Kalshi relative to Polymarket was because they were being suppressed by haters overwhelmingly taking the No for next year’s Super Bowl. It didn’t sit right. They’re literally America’s team. The Dream Team. The Miracle on Ice. Everybody loves them. I couldn’t rest until I got to the bottom of it.

When I was trying to figure out the cross-exchange spread story, one of the ideas I had explored was whether the difference in APYs (annual percentage yields—the interest they pay you on positions) was part of the explanation. This was actually a red herring because I didn’t RTFM closely enough to realize that Polymarket only pays APY on a very small set of handpicked long-term political markets. Everyone else gets nothing.

The impact of the risk-free rate on risky things

When you buy a position in a prediction market that resolves months from now, your money is effectively parked. It’s good to think of it that way because you don’t want to think about the money in terms of what it’s worth today, but rather what it would be worth if you put it into a risk-free Treasury instead. In other words, you should use that return (like 4.384%) as the true breakeven due to the opportunity cost.

The net effect of not having an APY is that it requires market takers (people buying positions to hold) to expect a discount relative to the price expected at settlement. If you evaluate a market settling in one year as truly being 50%, then you would price it fairly at the number that ends at 50% when compounded at the risk-free interest rate.

This is where the Polymarket problem comes in. Their negative risk approach has an innate incentive to snap the sum of all probabilities to 1.00. When all outcomes are trading for more or less than that dollar (accounting for all friction) then the arb bots pop in to bring the prices back in line.

But how can this work for long-term markets if every probability has to be discounted due to 0 APY? The short answer: it can’t. Prices have to move up to behave as though the risk-free rate isn’t a factor. But don’t take my word for it. Here are the insights you can extract from the top AI minds if you’re willing to take the time to dumb things down for them.

Grok

In a 0% APY 32-outcome NegRisk market settling in 1 year, the sum of Yes prices remains mechanically pinned at ~$1.00 with relative probabilities driven by information (same as a rewarded version), but in practice it suffers thinner liquidity, wider spreads, lower open interest from patient capital, and more short-term noise/drift due to the uncompensated opportunity cost of tying up money for a full year.

Gemini

A 1-year unrewarded multi-outcome market remains anchored to a $1.00 total via instant smart contract settlement, but the penalty of locking up capital without compensation drives away serious institutional market makers, leaving behind an illiquid order book characterized by wider spreads, shallow open interest, and erratic price swings from erratic retail flow.

Claude

API Error: 500 Internal server error. This is a server-side issue, usually temporary — try again in a moment. If it persists, check status.claude.com.

(Claude was being notably deterministic today.)

APY isn’t just a perk

Sure, APY is the platform handing some of that opportunity cost back to you. It isn’t a loyalty bonus. For a long-term market, it’s the thing that makes holding a position rational in the first place. Without it, a long-dated position isn’t just an investment with some expected return—it’s an investment you’re also quietly paying to hold.

While Polymarket limits their APY (4.0% right now) on a select few markets, Kalshi pays it (3.25%) on all market positions as well as cash. And while it’s nice to have for marketing purposes, it’s also crucial to the structural integrity of how these markets work.

What happens to a market with no APY

If holding a long-dated Polymarket position outside the political set means eating the full opportunity cost yourself, most traders simply won’t. And they don’t. The non-political long-term markets on Polymarket are markets in the technical sense, but there’s no real liquidity.

For example, the Seahawks market on Kalshi has been trading around 25-30x the Polymarket volume most days this offseason. On the other hand, the Polymarket for favorite JD Vance to win the 2028 election (which is one of the markets that does get APY) trades about $64,000 a day and dwarfs both of them despite not settling for an additional 21 months. It’s the same platform with the same general structure. The difference is APY.

What thin markets do to prices

And to dig in even further, let’s talk about the order books.

On Polymarket’s Vance market, moving the price by a single tenth of a percentage point—from 18.7% to 18.6%—takes roughly $600,000 of order flow. The market is deep enough to absorb a large trade without flinching.

On Polymarket’s Seahawks market, $30,000 doesn’t move the price—it ends it. It’s enough to buy up every No contract resting on the book. While new orders would likely come in immediately after, for that moment you could drop the Seahawks to 0%. And, in all likelihood, there wouldn’t be enough interest to bring them up to a true probability given the opportunity cost.

In other words, it would be pretty easy to manipulate the probabilities and keep them skewed for a long time. But an APY approaching the risk-free rate solves that, which is probably why Polymarket pays for it out of pocket for very visible political markets.

So is the Seahawks number wrong on Polymarket?

Probably. Kalshi has genuine interest and the lower carry cost, which makes its 8.5% the more trustworthy number. Polymarket’s 10.5% looks too high by comparison and doesn’t fit the “NegRisk pressures Yes to be cheaper on Polymarket” model the cross-exchange arb article suggests.

But here’s the point: you can’t do anything about it. To trade against the mispricing, you’d have to hold a position on Polymarket for nine months. On a market that pays you no APY. The carry cost you’d eat over those nine months is larger than the edge the mispricing offers. The price is wrong and uncorrectable at the same time because the same missing feature that let the price drift is the feature that makes the correction unprofitable.

Ironically, I was originally planning to write a piece exploring how and why there’s no such thing as option Greeks (and what I’m building to address that need for event contract investors). Instead, here I am, making the case for some sort of rho.

The takeaway

APY scope isn’t a footnote in a fee schedule. It’s a structural decision that has a meaningful impact on whether long-term markets properly function.

On a platform that pays APY across the board, long-term markets stay populated and their prices stay honest. On a platform that scopes APY to a chosen handful, the markets outside that scope stay shallow and you can’t really trust the numbers at any real granularity.

Make sure you know what you can trust.